The Diesel-Gasoline Chasm: Why Refiners are Shifting Gears in a Volatile Energy Market
By ANI | September 18, 2026
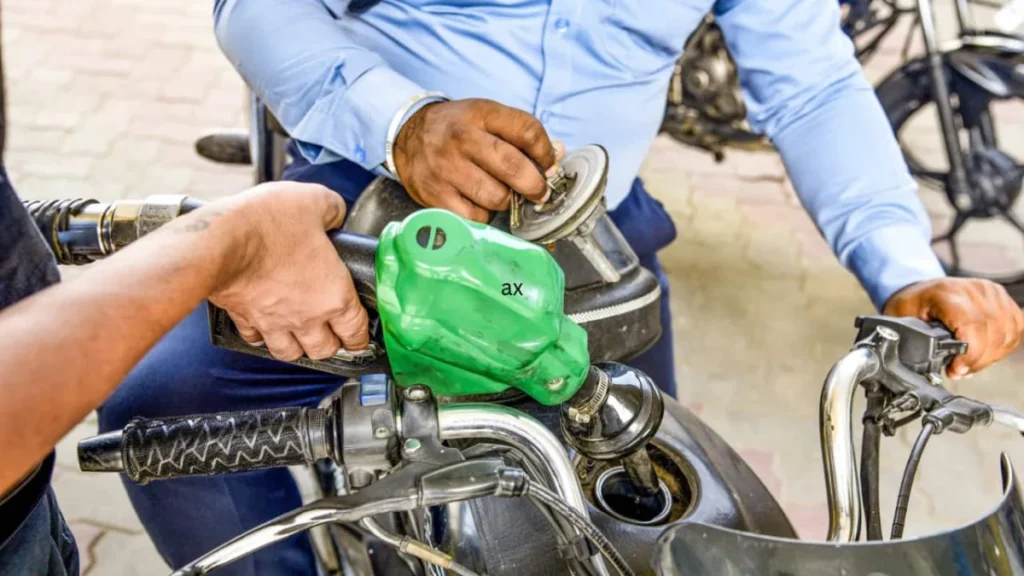
The global energy landscape is currently witnessing a tectonic shift in refinery economics, characterized by a staggering price divergence between two of the most critical transportation fuels: diesel and gasoline. As of September 2026, the price spread between US diesel and gasoline has ballooned to over USD 60 per barrel—a sharp contrast to the modest USD 3 spread observed just twelve months ago. This massive disparity is not merely a statistical anomaly; it is a fundamental reconfiguration of the market that is forcing refineries to prioritize diesel production at the expense of gasoline, potentially setting the stage for supply bottlenecks and price volatility in the retail sector.
The Widening Gap: A Chronology of Market Turbulence
To understand how the energy market arrived at this USD 60-per-barrel chasm, one must look back at the trajectory of the last year.
- September 2025: The market was in a state of relative equilibrium. Global demand for both fuels was recovering from post-pandemic fluctuations, and refinery margins were stable. The price difference between diesel and gasoline hovered at approximately USD 3 per barrel, a range that allowed refiners to operate with balanced production schedules.
- December 2025: Geopolitical tensions and shifting trade routes began to restrict the global flow of middle distillates. As winter demand for heating oil intensified in the Northern Hemisphere, diesel inventories began to show signs of structural tightness.
- March 2026: The first significant decoupling occurred. Industrial activity in key manufacturing hubs remained resilient, sustaining high demand for diesel, while gasoline consumption patterns shifted due to economic headwinds and increased adoption of electric and hybrid vehicles in suburban markets.
- June 2026: The spread widened significantly to USD 30. Refiners began to face pressure to optimize their "yield slates." Technical adjustments in the refining process—maximizing diesel extraction—led to an involuntary reduction in the volume of gasoline produced as a byproduct.
- September 2026: The current state of crisis. With a spread exceeding USD 60 per barrel, the market has reached a critical inflection point. Refineries are now operating under an overwhelming economic incentive to ignore gasoline volume in favor of the lucrative diesel market, fundamentally altering the global fuel supply chain.
Supporting Data: The Mechanics of Refinery Economics
Refineries are essentially complex chemical plants that process crude oil into various products through a process known as distillation. The "crack spread"—the difference between the price of the refined product and the cost of crude oil—is the primary metric for refinery profitability.
Current data indicates that while global crude oil prices have remained within a manageable range, the "diesel crack" has skyrocketed. Conversely, the "gasoline crack" has stagnated, or in some regions, compressed.
The Yield Dilemma
When a refinery operator decides to maximize diesel, they are not simply "choosing" to ignore gasoline. The chemical composition of the crude oil barrel dictates the potential output. To push for higher diesel yields, refiners must alter the temperature and catalysts in their catalytic crackers. This often results in a "lightening" of the barrel, where fewer high-value gasoline components are captured.
Global Export Declines
Compounding the local US issue is a global supply crisis. Reports indicate that global exports of refined products have dropped by approximately 24% year-over-year. This is driven by three factors:
- Refinery Maintenance: Extended maintenance cycles in major export hubs, including the Middle East and parts of Asia, have reduced the total volume of fuel hitting the international market.
- Increased Domestic Consumption: Developing economies are showing a higher-than-anticipated appetite for diesel to fuel industrial infrastructure and logistics, keeping domestic supplies within their respective borders.
- Sanctions and Trade Barriers: Ongoing restrictions on trade with major oil-producing nations have created a fragmented global market, where diesel is not flowing to where it is needed most, causing localized price spikes that reverberate back to the US.
Implications: A Dual-Fuel Crisis
The implications of this market structure are profound and multi-layered, affecting everything from industrial logistics to the average consumer’s wallet.
1. The Logistics and Inflationary Toll
Diesel is the lifeblood of the global economy. It powers the heavy-duty trucks, trains, and cargo ships that move 90% of the world’s goods. When the price of diesel spikes, the "cost of living" increases almost instantly. Every item on a supermarket shelf carries a diesel premium. If the USD 60 spread continues, we can expect a sustained inflationary pressure on consumer goods, as transportation companies pass these elevated fuel costs onto the final consumer.
2. The Gasoline Supply Paradox
While gasoline prices might appear stable or lower relative to diesel, this is a precarious stability. If refiners continue to maximize diesel at the expense of gasoline, the US could face a gasoline supply crunch during peak driving seasons. If the market shifts to a point where gasoline production is insufficient to meet demand, the price of gasoline will likely spike, not because of crude oil costs, but because of a simple lack of available product.
3. The Shift in Energy Investment
This volatility is sending a clear signal to the energy sector: the world is "short" on diesel. This is expected to drive a massive wave of capital expenditure toward hydrocracking technology—a process that converts heavier oil fractions into diesel. While this is a rational market response, it takes years to permit and build such infrastructure, meaning the volatility we see today is likely to persist for the foreseeable future.
Official Responses and Industry Outlook
Regulatory bodies and industry analysts remain cautious. A spokesperson for a major energy consultancy noted, "The market is currently punishing those who rely on a balanced production cycle. Refiners are acting rationally to maximize their margins, but the broader economic cost is a distortion of fuel prices that makes long-term logistics planning nearly impossible for small and medium-sized businesses."
Government officials are under mounting pressure to address the potential for a gasoline shortage. While no immediate government intervention (such as releasing strategic petroleum reserves) has been announced to specifically target the diesel-gasoline spread, agencies are monitoring refinery output closely. The consensus among energy analysts is that the government’s focus is on maintaining overall fuel availability, even if the price of specific products remains elevated.
Looking Ahead: The Long-Term Outlook
The current USD 60 spread is an outlier, but it represents a new reality in the post-2025 energy market. We are moving away from an era of "cheap and abundant" into an era of "efficient and targeted" refining.
For the average consumer, this means the days of low-cost fuel may be behind us. The volatility inherent in this spread suggests that the price at the pump will become increasingly decoupled from the price of a barrel of crude oil, governed instead by the complex, high-stakes decisions being made inside the control rooms of the world’s largest refineries.
As we look toward the remainder of 2026, the key question remains: will the market correct itself through a cooling of diesel demand, or will the gasoline supply drop so significantly that the two fuels find a new, albeit much higher, price equilibrium? For now, the global economy must brace for the impact of this unprecedented energy divide, navigating a path where the cost of moving goods may become the defining economic variable of the year.