The Hidden Price of Availability: Why Sunday Banking Operations Are Stirring Financial Controversy
By Tarique Anwar
Senior Sub-Editor
The recent decision to keep banking institutions operational on a Sunday, ostensibly to mitigate the impact of a three-day nationwide strike scheduled from September 28 to September 30, has triggered a heated debate regarding fiscal responsibility and operational efficiency. While the move was framed as a necessary measure to ensure service continuity for the general public, the financial ramifications are becoming increasingly difficult to ignore.
Preliminary estimates suggest that the direct cost of keeping branches open for this "special working day" has already crossed the Rs 160 crore mark. However, industry analysts and financial experts caution that this figure represents merely the tip of the iceberg. When factoring in the compounding expenses of branch maintenance, administrative overheads, security deployments, and electricity consumption, the final bill could climb significantly higher.
The Context: A Strategic Move Amidst Industrial Unrest
The banking sector in India serves as the backbone of the national economy. When unions announce industrial action—such as the massive three-day strike that crippled services between September 28 and September 30, 2026—the ripple effects are felt across every strata of society, from small-scale traders to large corporate entities.
The decision to operate on a Sunday, preceding the strike, was an attempt by banking authorities to clear the backlog of transactions and provide a window for customers to conduct urgent financial business. It was presented as a customer-centric initiative, a gesture of goodwill intended to demonstrate that the banking system remains resilient even when faced with organized labor challenges. Yet, beneath this veneer of service lies a complex economic reality that forces us to question: at what cost does "availability" come?
Chronology of the Operational Pivot
The timeline leading to the current fiscal predicament began weeks before the strike.
- Mid-September 2026: Banking unions finalize the call for a three-day nationwide strike, citing demands related to wage revisions, pension restructuring, and improved working conditions.
- September 25, 2026: Financial regulators and bank management boards hold emergency meetings to assess the potential damage to national financial flow. The directive to maintain operations on Sunday, September 27, is issued.
- September 27, 2026: Banks across the country open their doors for a rare Sunday shift. Staff are called in, and security protocols are heightened.
- September 28–30, 2026: The nationwide strike officially commences. Banking services largely come to a standstill, with ATMs running dry and clearing operations halted.
- October 1, 2026: Preliminary data begins to circulate, indicating that the Sunday operation alone cost the exchequer and private banking entities upwards of Rs 160 crore.
Breaking Down the Costs: The "Hidden" Expenses
To understand why the Rs 160 crore figure is considered a conservative estimate, one must look at the granular costs associated with operating a financial institution on a day designated as a public holiday.
1. Personnel and Overtime Pay
The most significant component of the expenditure is the additional remuneration for employees. Working on a Sunday typically mandates double-time pay, special allowances, and compensation leave. When multiplied by the hundreds of thousands of bank employees across the nation, the payroll burden is immense.
2. Infrastructure and Utilities
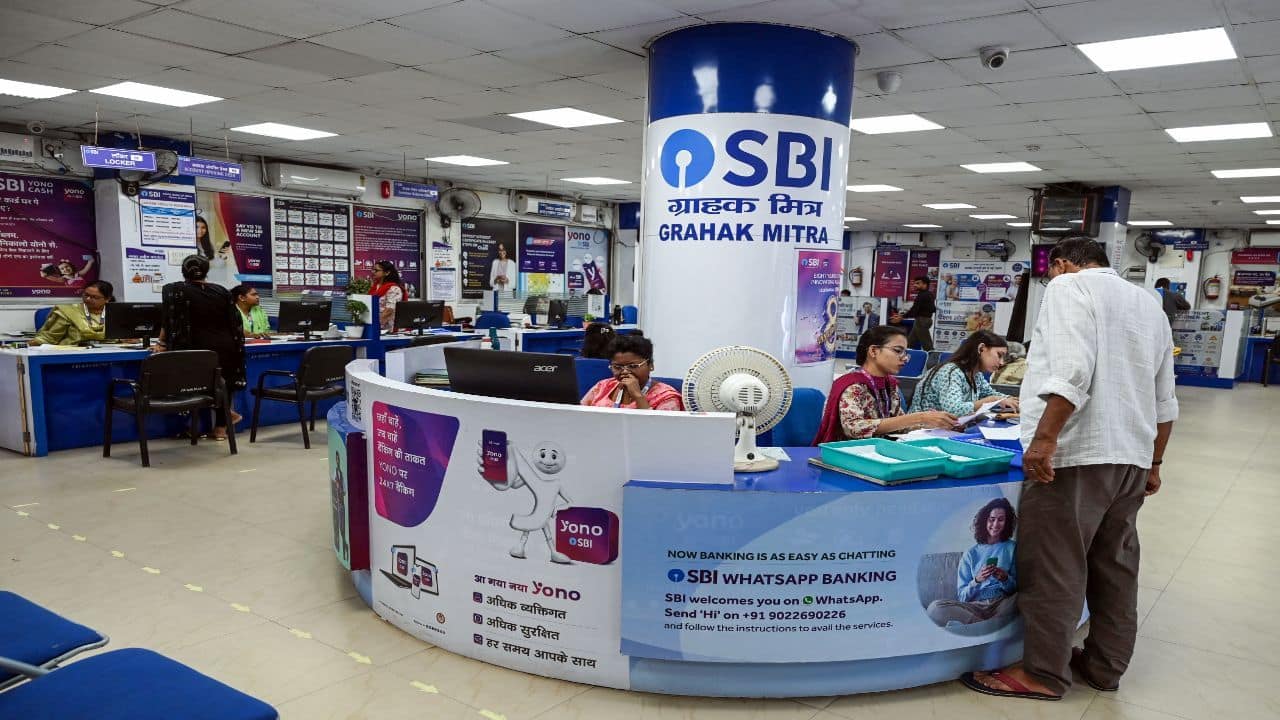
Banking branches are not just desks and chairs; they are high-tech hubs requiring constant climate control, high-speed data connectivity, and robust security systems. Running these systems on a day when they would otherwise be powered down results in substantial utility bills. Furthermore, if a branch is situated in a leased commercial space, there are additional costs associated with building-wide security and maintenance services that must be activated on demand.
3. Security and Logistics
Cash management services (CMS)—the companies responsible for replenishing ATMs and transporting currency—operate on strict schedules. Shifting these operations to a Sunday requires premium scheduling, overtime for armed guards, and additional insurance premiums for the transportation of liquid assets.
4. Administrative Overheads
The logistics of coordinating a workforce, managing customer complaints, and overseeing compliance on a non-working day requires management presence. This often leads to "management creep," where senior officials are also required to be present, further inflating the administrative cost of the day.
The Economic Implications: Efficiency vs. Service
The core of the issue lies in the tension between service delivery and cost efficiency. Banking, while a service industry, is also a business. When operational costs exceed the value of the transactions processed during the additional hours, the business suffers.
Critics argue that the Rs 160 crore expenditure could have been better utilized in digital infrastructure. As the world moves toward a 24/7 digital banking ecosystem, the necessity of keeping physical branches open on a Sunday is being questioned. If the sector invested more in robust, failsafe digital gateways, the reliance on physical branches during industrial strikes could be minimized, thereby saving hundreds of crores during future labor disputes.
Conversely, supporters of the Sunday initiative point to the "inclusive" nature of the move. A significant portion of the Indian population—particularly in rural and semi-urban areas—still relies heavily on physical banking for basic transactions. For these individuals, a three-day strike without a preceding Sunday window would have meant an absolute freeze on their financial mobility.
Official Responses and Stakeholder Views
The silence from banking regulatory bodies regarding the final, total cost of the operation has been notable. While the Rs 160 crore figure was confirmed by internal reports, official statements have largely focused on the "success" of the outreach rather than the fiscal burden.
Union leaders have expressed skepticism about the motives behind the Sunday opening. Many argue that the decision was a tactical move to weaken the perceived impact of the strike. By providing a temporary relief valve, management sought to dilute the public pressure that usually forces the government to the negotiating table.
"The cost of keeping branches open on Sunday is a waste of resources that could have been used to address the very grievances that led to the strike in the first place," said one union representative.
The Road Ahead: A Call for Sustainable Banking
The events of late September 2026 serve as a stark reminder that the banking sector needs a more sustainable approach to labor relations and operational management. The current strategy of "throwing money at the problem"—by paying for extra working days to mitigate strike impacts—is a short-term fix that masks deeper structural issues.
If the banking industry is to remain competitive and cost-effective, it must navigate three critical paths:
- Digital Resilience: Accelerating the shift toward fully autonomous digital banking to ensure that physical strikes do not result in total financial paralysis.
- Proactive Conflict Resolution: Establishing a more efficient mechanism for salary and pension negotiations to prevent the need for nationwide strikes in the first place.
- Fiscal Transparency: Publicly auditing the costs of contingency operations to ensure that shareholder and taxpayer money is not being squandered on performative operational measures.
As the dust settles on the September strike, the banking sector faces a pivotal moment. The Rs 160 crore bill is a painful lesson in the price of emergency operations. Whether this will lead to a more pragmatic approach in the future remains to be seen. What is clear, however, is that the era of simply absorbing these costs without scrutiny is coming to an end. The stakeholders, the public, and the economy demand more than just open doors; they demand a system that is as fiscally responsible as it is accessible.