Gold Market Outlook: Navigating Volatility Amidst Persistent Inflation and Hawkish Fed Signals
By Sandal Khan | Business Desk
Updated: October 12, 2026
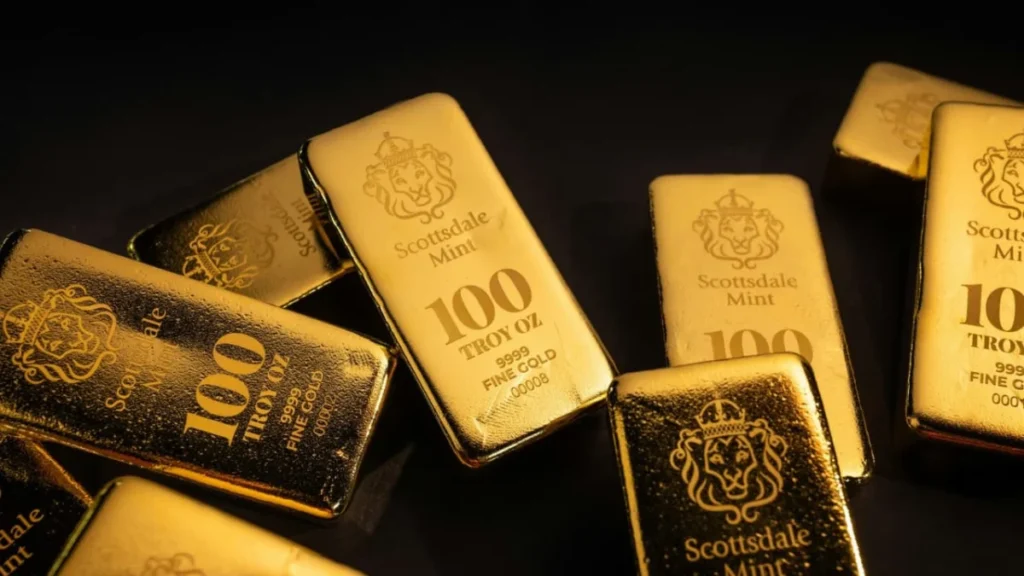
The global precious metals market has entered a period of heightened sensitivity as gold prices fluctuate in response to shifting macroeconomic indicators. As of October 12, 2026, the yellow metal is navigating a turbulent landscape defined by persistent inflation data and the looming specter of further interest rate hikes by the United States Federal Reserve. For investors, traders, and everyday consumers, the current market climate reflects a tug-of-war between gold’s traditional role as a safe-haven asset and the growing pressure from rising opportunity costs associated with yield-bearing instruments.
Main Facts: The Current State of the Gold Market
The gold market has experienced significant price swings over the past several weeks, a direct reaction to the dual pressures of sticky inflation and a shifting narrative from the U.S. central bank. Gold, which historically thrives in environments of low interest rates and high inflation, has found itself struggling to maintain momentum.
When the Federal Reserve signals a commitment to tightening monetary policy, the U.S. Dollar typically strengthens, and yields on Treasury bonds rise. Because gold is a non-yielding asset, its appeal diminishes when investors can earn reliable returns elsewhere. This current divergence—where inflation remains stubbornly above the target, yet the Fed remains hawkish—has created a "volatile floor" for gold prices. Market analysts note that while the demand for physical gold in major hubs like India remains resilient, the global spot price is tethered to the whims of U.S. economic policy.
Chronology of Market Turbulence
The volatility observed in early October is not an isolated event but rather the culmination of several months of economic data releases.
- Mid-August 2026: Markets began pricing in a more aggressive stance from the Fed following stronger-than-expected labor market data. Gold prices began a gradual descent from their mid-year highs.
- Early September 2026: Inflation data released for August showed a surprise uptick, catching many analysts off guard. This prompted a sharp, immediate sell-off in gold as the market braced for a "higher for longer" interest rate environment.
- Late September 2026: A brief period of geopolitical instability in the energy sector provided a temporary boost to gold, showcasing its utility as a hedge against systemic shocks.
- Early October 2026: As the Federal Reserve’s next policy meeting approaches, anticipation of a 25-basis-point hike has kept the market in a state of flux. Prices have hovered in a tight range, reacting sensitively to every speech by Fed officials and every major CPI (Consumer Price Index) report.
Supporting Data: Why Gold is Struggling
The relationship between interest rates and gold is inversely correlated. Data from the last quarter shows that as the U.S. 10-year Treasury yield climbed toward the 4.5% threshold, gold’s ability to sustain price levels above the $2,000 per ounce mark was severely tested.
Furthermore, the strength of the U.S. Dollar Index (DXY) has been a primary headwind. Gold is priced in dollars; when the dollar rises, gold becomes more expensive for international buyers holding other currencies, thereby dampening global demand. Commodity desk reports indicate that institutional outflows from Gold ETFs (Exchange Traded Funds) have increased significantly, signaling that professional investors are rotating their capital into short-term government bonds to capitalize on higher interest rates.
Despite this, physical demand in the Asia-Pacific region continues to act as a stabilizer. Data from major bullion dealers suggests that despite price dips, there is robust "buying on the dip" behavior, particularly among central banks in emerging markets that are looking to diversify their reserves away from the U.S. dollar.
Official Responses and Monetary Policy Outlook
Federal Reserve officials have remained largely consistent in their messaging. The consensus among the Board of Governors is that while headline inflation has moderated from its 2025 peaks, "core" inflation remains uncomfortably high.
In recent briefings, Fed Chair Jerome Powell emphasized that the central bank’s primary mandate remains the restoration of price stability. "We are prepared to adjust our policy stance if necessary," a representative noted during the most recent FOMC (Federal Open Market Committee) press conference. "We cannot afford to declare victory over inflation prematurely."
For the gold market, this rhetoric is a double-edged sword. On one hand, the Fed’s commitment to curbing inflation is necessary for long-term economic stability. On the other hand, the refusal to pivot toward rate cuts keeps the "cost of carry" high for gold holders. Most analysts now expect the Fed to maintain current rates through at least the first quarter of 2027, unless a significant recessionary signal emerges.
Implications for Investors and Consumers
The implications of this market environment are twofold: one for the long-term investor, and another for the short-term market participant.
For the Long-Term Investor
Financial advisors continue to suggest that gold should constitute a small, fixed percentage (usually 5–10%) of a well-diversified portfolio. In periods of high volatility, the goal is not necessarily to profit from short-term price movements, but to protect the portfolio from unexpected market shocks. The current volatility, while unsettling, does not negate gold’s historical function as a hedge against currency debasement and geopolitical uncertainty.
For the Short-Term Participant and Consumer
Those looking to purchase gold for personal use, such as jewelry or gifting, may find the current volatility advantageous. Prices in major metropolitan markets—including Delhi, Mumbai, and other commercial hubs—have shown fluctuations that allow for strategic purchasing. Consumers are advised to monitor the daily spot rates and consider buying in smaller, staggered increments rather than attempting to "time the market" for the absolute lowest price.
The Path Ahead: What to Watch
As we move into the final quarter of 2026, the gold market will be driven by three critical factors:
- Inflation Reports: Any sign that inflation is cooling faster than expected will likely lead to a swift recovery in gold prices.
- Labor Market Strength: The Fed’s policy is heavily data-dependent. A significant cooling in the labor market would force the Fed to soften its stance, which would be an immediate bullish signal for gold.
- Geopolitical Stability: In an increasingly interconnected world, any escalation in regional conflicts or disruptions to global supply chains will inevitably drive investors back to the safety of precious metals.
In conclusion, while the immediate horizon is clouded by the pressure of rising interest rates, gold remains a cornerstone of financial security. The current volatility is a reflection of a global economy in transition—a period where old certainties are being challenged, and investors are being forced to navigate a more complex, interest-rate-sensitive landscape.
As the market continues to process incoming data, the savvy observer will look beyond the daily price ticker. The true value of gold in 2026 lies not in its ability to generate quick returns, but in its persistent, time-tested role as a stabilizer in a world that refuses to stand still. Investors and consumers alike should remain cautious, stay informed, and maintain a long-term perspective as the Federal Reserve and global markets continue their high-stakes game of monetary chess.
Disclaimer: This report is for informational purposes only and does not constitute financial advice. Investors should consult with a qualified financial advisor before making any investment decisions.