NEW DELHI — The Indian smartphone market, traditionally one of the most resilient and fast-growing consumer technology sectors in the world, has suffered a historic downturn. According to the latest comprehensive market intelligence report from Counterpoint Research released on October 23, 2026, India’s smartphone shipments plummeted by a staggering 20% year-over-year (YoY) during the third quarter (July–September) of 2026. This sharp contraction has dragged shipments down to a dismal decade-long low for the crucial third-quarter period.
The primary catalysts behind this unprecedented collapse are skyrocketing memory prices, mounting component inflation, and subsequent retail price hikes that severely crippled affordability across the mass-market segments. While premium brands and Apple’s latest flagship lineup found pockets of exceptional growth, the foundational volume drivers of the Indian market buckled under economic pressure.
1. Main Facts: The Anatomy of a Market Collapse
The third quarter is historically the most lucrative period for consumer electronics in India, heavily anchored by preparations for the festive shopping season, which includes major retail milestones like Diwali and Dussehra. However, Q3 2026 defied historical trends, transforming from a peak season of high anticipation into a period of acute inventory stagnation and depressed consumer appetite.
Historic Contraction: Overall smartphone shipments fell by 20% YoY during Q3 2026, marking the lowest third-quarter volume recorded in the country in ten years.
The Cost Crisis: Unprecedented spikes in global memory and component costs forced Original Equipment Manufacturers (OEMs) to continuously raise retail prices, pricing out millions of budget-conscious buyers.
Mass Market Devastation: The sub-₹20,000 price band experienced a catastrophic 47% decline in shipments as device costs forced models into higher pricing tiers.
Samsung Reclaims the Crown: Breaking a nine-quarter drought, Samsung surged back to the top of the Indian smartphone market, capturing a 17% market share driven primarily by the sustained popularity of its Galaxy A series.
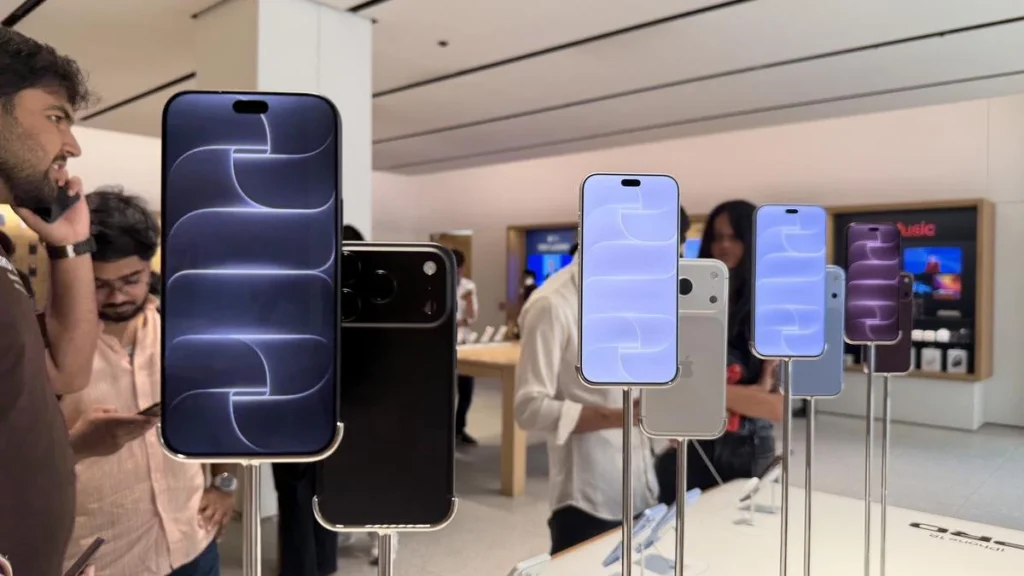
Apple’s Premium Resilience: The newly launched Apple iPhone 18 Pro series recorded a stellar debut, posting initial sales nearly 20% higher YoY compared to its predecessor, the iPhone 17 Pro series.
2. Chronology: How the Q3 2026 Crisis Unfolded
To understand how India’s smartphone industry reached this historical inflection point, one must look at the compounding macroeconomic and supply chain pressures that built up over the preceding quarters.
Early 2026: Supply Chain Strains and Component Inflation
As the global technology sector navigated persistent supply chain adjustments through the first and second quarters of 2026, memory manufacturers—driven by the exponential demands of artificial intelligence (AI) infrastructure and high-performance data centers—began redirecting manufacturing capacity. This triggered a severe global supply crunch for DRAM and NAND flash memory. By late Q2, component costs for mobile OEMs began to climb at an unsustainable rate.
July 2026: The Onset of Q3 and Inventory Accumulation
As Q3 commenced in July, smartphone brands were forced to make a difficult choice: absorb the soaring costs and watch profit margins evaporate, or pass the expenses onto consumers. Most OEMs chose the latter. However, retail demand immediately softened. Consumers accustomed to value-packed devices in the sub-₹15,000 and sub-₹20,000 brackets were greeted with inflated price tags or downgraded specifications. Consequently, channel partners and retailers found themselves holding excess inventories as sell-through rates plummeted.
August to September 2026: Festive Preparation Fails to Ignite
Traditionally, August and September witness heavy inventory loading by distributors ahead of the grand online and offline festive sales. In 2026, this standard seasonal surge was muted. Retailers, wary of unsold stock from the summer months, adopted a cautious stance. Even as brands attempted to stimulate demand with early festive promotions, the structural barrier of high baseline device prices kept discretionary buyers at bay, culminating in the disastrous final numbers reported at the close of September.
3. Supporting Data: Market Shares and Brand Performance
The contraction of the broader market drastically reshuffled the competitive landscape among OEMs, highlighting a stark divergence between the struggles of the mass-market volume drivers and the resilience of ultra-premium players.
Brand Rankings in Q3 2026
Samsung (17% Market Share): Reclaiming the number one spot in India for the first time in nine quarters, Samsung capitalized on its robust distribution network and the consistent volume-driving capabilities of its mid-range Galaxy A series. The brand’s ability to maintain supply chain stability better than some of its competitors helped it weather the market storm.
Vivo (16% Market Share): Securing the second position, Vivo remained a dominant force in the offline retail sector. Its popular Y-series continued to move units, though the brand was not immune to the overarching contraction in lower-tier pricing segments.
Oppo (12% Market Share): Holding steady at third place, Oppo focused on targeted marketing and camera-centric offerings to sustain consumer interest amid difficult macroeconomic conditions.
Xiaomi (12% Market Share): Once the undisputed titan of the Indian online budget market, Xiaomi faced severe headwinds. Because a massive portion of its traditional portfolio sits in the sub-₹15,000 bracket—the segment hit hardest by memory price inflation—Xiaomi’s shipment volumes contracted significantly, tying it with Oppo at 12%.
The Premium and Niche Bright Spots
While the mass market floundered, the upper echelons of the market exhibited surprising strength:
Apple: The tech giant enjoyed exceptional momentum. The iPhone 18 Pro series achieved a stellar debut, with early sales tracking approximately 20% higher than the iPhone 17 Pro series during the same launch window. Furthermore, older generations, particularly the iPhone 17 lineup, continued to experience healthy demand even after strategic price adjustments by Apple across its broader portfolio.
Google: Demonstrating impressive growth against the market trend, Google recorded over 50% YoY growth in India during Q3, driven by aggressive marketing of its Pixel ecosystem and expanding brand recall.
Chipset Market Dynamics: In the semiconductor space, MediaTek retained its dominance as the leading chipset OEM in India during Q3 2026, capturing a commanding 45% market share by powering a vast array of mainstream and mid-tier devices despite component cost pressures.
4. Official Responses and Expert Analysis
Industry analysts and market researchers have offered sobering assessments of the current crisis, emphasizing that structural shifts in component pricing have fundamentally altered consumer behavior in South Asia’s most vital digital economy.
"Rising component costs pushed device prices higher, putting increasing pressure on affordability and weakening the traditional mass-market volume engine, particularly below ₹15,000," explained Shubham Singh, Research Analyst at Counterpoint Research.
Elaborating on the severity of the price migration, Singh added:
"Sub-₹20,000 shipments declined by a staggering 47% in Q3 2026 as rising model prices pushed devices into higher price bands, effectively alienating the entry-level consumer base."
Looking ahead at the remainder of the year and into the immediate future, industry leadership remains deeply cautious. Tarun Pathak, Research Director at Counterpoint Research, warned that the road to recovery will be arduous and protracted.
"We expect India’s smartphone market to shrink by around 13% for the full year 2026, with continued pricing pressure weighing heavily on affordability and replacement demand," Pathak stated.
Addressing the post-festive outlook, Pathak cautioned that structural economic realities will continue to squeeze both manufacturers and consumers:
"The post-festive seasonal slowdown will add to the pressure, while elevated component costs are likely to drive another round of price hikes after the festive season sales conclude."
5. Implications: What This Means for the Future of India’s Tech Ecosystem
The collapse of smartphone shipments to a decade-low level carries profound implications for the Indian technology landscape, stretching far beyond quarterly corporate earnings reports.
The Threat to Digital Inclusion and Upgrades
India’s rapid digital transformation over the past decade has been built on the back of affordable, feature-rich smartphones priced under ₹15,000. These devices serve as the primary gateway for hundreds of millions of citizens accessing digital payments, e-governance portals, remote education, and digital entertainment. When sub-₹20,000 shipments contract by 47%, it directly impedes first-time smartphone adoption and slows down the natural upgrade cycles of existing users. Prolonged retention of aging devices could stall the growth of India’s digital economy.
Margin Squeeze and Strategic Pivots for OEMs
For smartphone manufacturers, the current environment is an existential test of supply chain management and portfolio strategy. Brands that rely entirely on low-margin, high-volume budget models are facing severe revenue losses. Consequently, many OEMs are being forced to pivot their strategies upward toward premiumization. By focusing on higher-margin devices—such as mid-to-high tier flagships, foldables, and AI-integrated hardware—manufacturers hope to offset declining unit volumes with higher average selling prices (ASPs). However, this shift risks abandoning the bedrock mass market altogether.
Manufacturing and Local Sourcing Pressures
India’s ambitious push to become a global hub for electronics manufacturing (under initiatives like the Production-Linked Incentive [PLI] scheme) faces a psychological hurdle amidst slumping domestic demand. While local assembly lines continue to export significant volumes of devices to Western markets, a depressed domestic market means local component suppliers and assembly plants cannot rely on internal consumption to cushion external global economic shocks.
Conclusion
As India enters the final stretch of 2026, the smartphone industry stands at a critical crossroads. The Q3 collapse serves as a stark reminder that consumer technology adoption is intrinsically tied to macroeconomic affordability. Unless global memory and component costs stabilize, or manufacturers find innovative ways to engineer cost-effective hardware without compromising core utility, the path to market recovery will be long, challenging, and marked by a permanent reshaping of how India buys and uses mobile technology.