Global Smartphone Market Suffers Historic 20% Plunge in Q3 2026 Driven by Severe Memory Chip Shortages and Rising Component Costs
By Global Technology Desk
Published: October 12, 2026, 05:35 PM IST
Main Facts: A Historic Collapse in Global Handset Volumes
The global mobile device ecosystem experienced one of the most turbulent quarters in its history during the third quarter (Q3) of 2026. According to comprehensive market intelligence data released by Counterpoint Research, worldwide smartphone shipments plummeted by a staggering 20% year-over-year (YoY), registering the lowest total shipment volume for a third quarter since 2012.
The primary catalyst behind this unprecedented contraction was an exponential surge in the cost of memory chips, which directly inflated the Bill of Materials (BOM) for original equipment manufacturers (OEMs). This compounding financial pressure triggered severe supply chain bottlenecks, forced widespread production adjustments, and disrupted OEM fulfillment schedules globally.
Rather than absorbing these escalated production expenses, major handset manufacturers passed the financial burden directly onto end-users. Consequently, global smartphone retail prices surged by an average of 20% over the course of 2026, driving the market’s Average Selling Price (ASP) to new historical highs.
Despite the universally challenging macroeconomic and supply environment, market leaders managed to adapt with varying degrees of resilience. Samsung maintained its dominance at the top of the global rankings, while Apple secured a record-breaking market share for a third-quarter period. Conversely, major Chinese Android heavyweights—including Xiaomi, Oppo, and Vivo—faced sharp double-digit shipment declines as price-sensitive consumer segments balked at sudden retail price hikes.
Chronology: How the Q3 2026 Crisis Unfolded
To understand how the global smartphone market arrived at its lowest third-quarter shipment volume in fourteen years, it is necessary to examine the cascading events that unfolded throughout late 2025 and the first three quarters of 2026:
- Late 2025 – Early 2026: The Squeezing of Component Pipelines
Early warnings emerged in the semiconductor manufacturing sector as soaring demand for enterprise-grade artificial intelligence hardware crowded out fabrication lines traditionally allocated for mobile memory (DRAM and NAND flash). Lead times for critical components doubled, laying the groundwork for a severe inventory squeeze. - Q1 – Q2 2026: Escalating BOM and First Price Corrections
By the end of the second quarter, rising memory chip prices had driven up BOM costs to unsustainable levels for budget and mid-range devices. OEMs began implementing quiet price adjustments across entry-level portfolios. Initial consumer resistance was moderate, but sales velocity began to taper off in developing markets. - July – August 2026: The Manufacturing Bottleneck and Strategic Shifts
Entering the third quarter, component shortages intensified. OEMs across the board instituted production cuts to protect operating margins. In response to margin compression, brands like Oppo moved aggressively to consolidate their sub-brand operations (Oppo, Realme, and OnePlus), seeking to eliminate internal product overlap and maximize procurement efficiencies. - September 2026: Flagship Launches and Portfolio Gaps
As the traditional autumn product launch cycle commenced, shipments were severely hampered. Apple’s decision to bypass a traditional "base" model for its iPhone 18 lineup created a volume gap in its distribution pipeline. Meanwhile, budget models from brands like Vivo were pushed entirely out of their historical price brackets due to cumulative cost inflation, resulting in vacant retail shelf space and plunging volume metrics. - October 12, 2026: Counterpoint Research Releases Q3 Data
Counterpoint Research officially published its quarterly report, confirming the 20% YoY market contraction, cementing Q3 2026 as the worst third quarter for smartphone shipments since 2012, and signaling that relief is unlikely in the near term.
Supporting Data: Market Share, Shipments, and Pricing Metrics
The structural shift in the global smartphone landscape is vividly illustrated by the performance metrics of individual market participants during Q3 2026:
1. Samsung Electronics (Top Spot Retained)
- Year-over-Year Shipment Change: -3%
- Global Market Share: 23%
- Analysis: Despite a marginal decline in absolute shipment volume, Samsung successfully retained its position as the world’s leading smartphone vendor. By strategically balancing its robust Galaxy S-series premium portfolio with resilient regional demand for its Galaxy A-series, Samsung actually expanded its total global market share by securing a larger slice of a shrinking pie.
2. Apple Inc. (Record Q3 Market Share)
- Year-over-Year Shipment Change: Moderate decline in volume
- Global Market Share: 22%
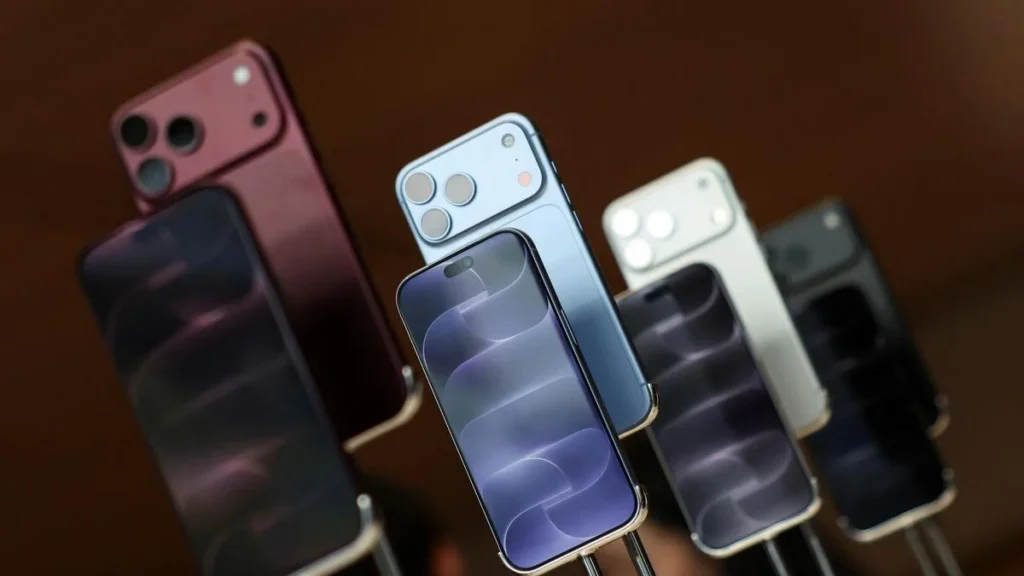
- Analysis: Apple achieved a historic milestone in Q3 2026 by capturing over 20% of the global market share for the first time ever during a third-quarter reporting period. This was accomplished despite an overall dip in hardware volume, which Counterpoint attributed largely to strategic portfolio adjustments—specifically, the deliberate absence of a base-tier iPhone 18 model at launch. This channeled consumer demand toward higher-priced Pro and Pro Max configurations, lifting ASPs significantly.
3. Xiaomi Corporation (Steep Contraction)
- Year-over-Year Shipment Change: Exceeded -30%
- Global Market Share: 10%
- Analysis: Xiaomi bore the brunt of the consumer pullback in budget and entry-level segments. With shipments diving by more than 30% YoY, the company’s market share contracted to 10%. The brand struggled to maintain its traditional volume-driven business model as memory chip expenses priced its ultra-affordable offerings out of reach for core demographics.
4. Oppo and Vivo (Defensive Retrenchment)
- Oppo YoY Shipment Decline: >20% | Market Share: 9%
- Vivo YoY Shipment Decline: >20% | Market Share: 8%
- Analysis: Both Oppo and Vivo saw their shipments drop by over 20% compared to Q3 2025. Oppo responded by aggressively consolidating its multi-brand framework—tightening operational integration across Oppo, Realme, and OnePlus. Vivo concentrated its operational footprint primarily on key high-volume growth territories like India and China, reinforcing its value-oriented Y series while trying to push upward into premium tiers with its X, V, and S series. However, persistent stock shortages and unavoidable price hikes severely capped their total output.
Official Responses and Industry Insights
Market analysts and industry stakeholders have offered stark assessments of the structural forces shaping the electronics retail and manufacturing sectors.
In its official research note, Counterpoint Research emphasized that the current crisis is fundamentally rooted in supply-side economics rather than a sudden evaporation of consumer desire for mobile technology. “OEMs have been left with very little room to maneuver. When component costs spike this aggressively, manufacturers are forced to choose between absorbing unsustainable losses or passing the costs to the consumer. Most chose the latter, which inevitably depressed overall volumes,” the research note stated.

Retailers specializing in consumer electronics have voiced similar concerns. In related commentary highlighted by industry analysts regarding electronic retail supply chains, experts noted that consumer financing mechanisms and digital payment monetization models have been strained as higher retail prices lengthen replacement cycles. Consumers are holding onto older devices significantly longer, treating smartphones as durable investments rather than frequently upgraded consumer goods.
Supply chain executives, speaking on condition of anonymity, indicated that foundries are currently prioritizing high-margin AI accelerators and data center components over mobile-grade DRAM and flash memory. Until wafer allocation shifts back toward consumer electronics, component scarcity will remain the defining bottleneck for the mobile industry.
Implications: What Lies Ahead for the Global Smartphone Industry?
The profound disruptions recorded in Q3 2026 carry long-lasting implications for manufacturers, retailers, and consumers alike:
1. Permanent Shift Toward Premiumization
With entry-level and mid-range margins permanently compressed by higher BOM costs, OEMs are fundamentally rethinking their product roadmaps. Brands are increasingly deprioritizing low-margin, high-volume models in favor of premium devices where margins can better absorb component price volatility. This trend suggests that the era of ultra-cheap, feature-rich budget smartphones may be drawing to a close, at least for the medium term.
2. Protracted Recovery Timeline
Industry consensus points toward a prolonged stagnation in overall unit shipments. Counterpoint Research explicitly warned that "a meaningful recovery in overall volumes is unlikely until component costs and supply conditions improve." With semiconductor fabrication plants locked into long-term capital expenditure cycles geared toward enterprise AI infrastructure, a stabilization in mobile memory pricing is unlikely to materialize before late 2027.
3. Consolidation and Market Rationalization
Smaller and regional smartphone brands face an existential threat. As seen with Oppo’s portfolio rationalization, surviving the current downturn requires ruthless operational efficiency, supply chain muscle, and the ability to cross-subsidize hardware lines. Expect further industry consolidation, strategic partnerships, and potential exits as weaker players find themselves unable to compete in a high-cost environment.
4. Consumer Behavior and Extended Replacement Cycles
For the average consumer, the immediate takeaway is higher retail pricing and fewer choices in the budget tier. As average selling prices climb past historical ceilings, buyers are adapting by extending their device upgrade cycles well beyond the traditional two-to-three-year window. Refurbished and second-hand smartphone markets are expected to see a corresponding surge in demand as cost-conscious consumers seek alternatives to brand-new hardware.
As the industry navigates the final quarter of 2026, all eyes remain on semiconductor fabrication plants and major OEMs to see whether production adjustments can restore balance to a fractured global supply chain.