Indian Startup Funding Slumps 82% to $58.9 Mn as Macroeconomic Caution and Regulatory Debates Take Center Stage
NEW DELHI — The Indian startup ecosystem experienced a sharp contraction in venture capital deployment this week, pulling back dramatically from the high-octane deal-making witnessed earlier in the month. While industry stakeholders remained preoccupied with heavy regulatory discourse—most notably the intense debate surrounding the potential introduction of Merchant Discount Rates (MDR) on Unified Payments Interface (UPI) transactions—investors adopted a notably conservative posture.
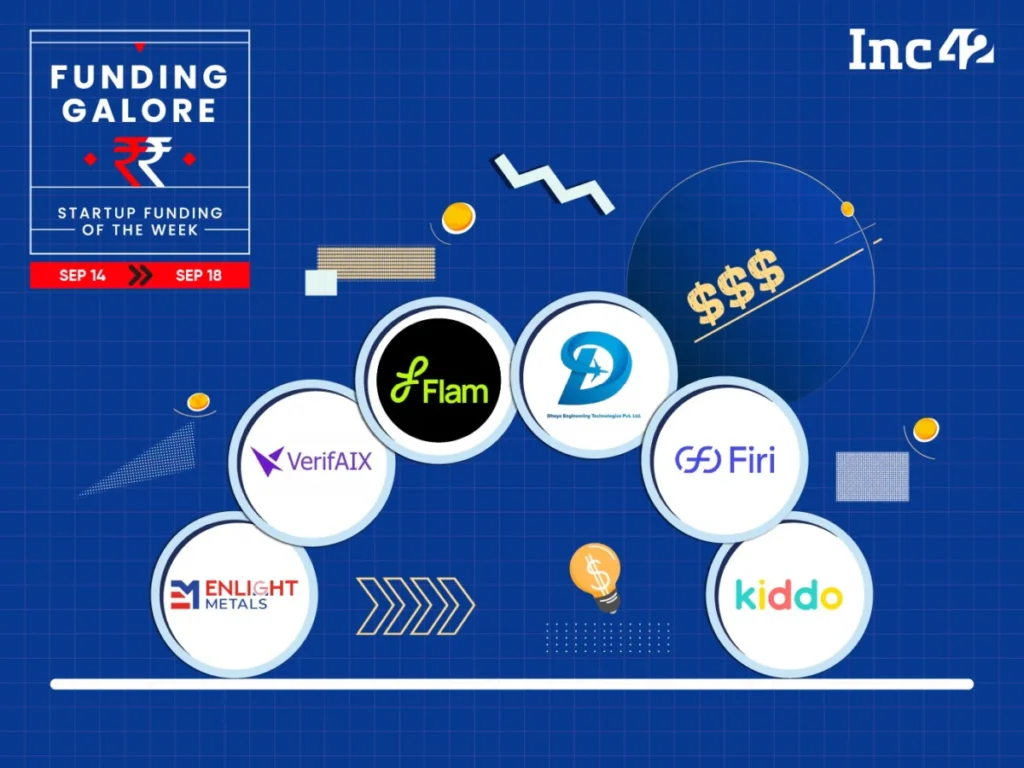
According to proprietary funding data tracking the period from September 14 to September 18, 2026, a total of 12 startups successfully secured $58.9 Mn across various funding rounds. This represents a staggering 82% decline compared to the preceding week, during which Indian startups pulled in an impressive $321.9 Mn.
Despite the broad-based slowdown in aggregate capital inflow, strategic venture capital activity persisted. Micro-VC funds, deeptech syndicates, and specialized sector-focused vehicles continued to lay long-term bets, even as late-stage transactions dried up temporarily.
Main Facts: The Anatomy of This Week’s Funding Slump
The headline figure of $58.9 Mn underscores a cooling-off period for the world’s third-largest startup ecosystem. However, raw aggregate numbers rarely tell the complete story of a dynamic market.
A closer examination of the weekly ledger reveals that capital concentration remains heavily skewed toward enterprise tech and high-margin B2B models, even as early-stage consumer brands fight for survival in hyper-competitive segments like quick commerce and direct-to-consumer (D2C) retail.
- Total Capital Raised: $58.9 Mn (down 82% week-on-week from $321.9 Mn).
- Total Active Deals: 12 disclosed funding transactions involving unique startups (though raw tracking tables note 14 total entries, inclusive of strategic and undisclosed rounds).
- Dominant Sector: Enterprise Services and Advertising led the charts, largely propelled by a single massive Series B transaction.
- Most Active Investor: AJVC emerged as the most prolific micro-VC of the week, writing checks across multiple early-stage ventures including MoroMaa, Slayd, and Beijan.
- Macro Backdrop: Regulatory headwinds, structural discussions regarding digital payments, and cautious deployment strategies by institutional limited partners (LPs) heavily influenced investor sentiment.
Chronological Breakdown of the Week’s Deals (Sep 14 – Sep 18, 2026)
Deal-making was spread unevenly across the five-day trading and investment window, with mid-week announcements accounting for the majority of the deployed capital.
Tuesday, September 15, 2026
- Flam (Enterprise Services / Advertising – B2B): In the single largest transaction of the week, advertising-tech innovator Flam secured $40 Mn in a Series B funding round comprising a mix of primary and secondary capital transactions. The round was spearheaded by QED Investors, with heavy participation from RTP Global, Dovetail, the family office of Bollywood icon Shah Rukh Khan, Claypond Capital, and Australian Gulf Capital. Noted angel investors Martin Chavez and Olivier Pomel also participated. Flam’s ability to pull in global institutional heavyweights underscores enduring investor appetite for scalable enterprise-facing advertising solutions.
- Darwinbox (Enterprise Tech / Horizontal SaaS – B2B): Human resources technology unicorn Darwinbox secured a strategic infusion from Teachers’ Venture Growth (TVG). While the financial terms of the transaction were undisclosed, the backing by TVG signals continued confidence in enterprise software-as-a-service (SaaS) plays expanding across global markets.
Wednesday, September 16, 2026
- VerifAIX (Advanced Hardware & Tech / Semiconductor – B2B): Deeptech and semiconductor innovation received a vital boost as VerifAIX closed a $5 Mn Seed round. The round was co-led by Endiya Partners and Bluehill VC, highlighting growing institutional interest in India’s nascent hardware and semiconductor design ecosystem.
- Firi (Consumer Services / Quick Commerce – B2C): Operating in the fiercely contested quick-commerce landscape, Firi secured $3 Mn in a Seed funding round. 360 ONE Asset led the round, backed by Better Capital and prominent angel investor Kunal Shah.
- TRUE ARTIS (Health Tech / In-Clinic Healthcare – B2C): Seeking to transform clinical healthcare delivery, TRUE ARTIS raised $1.2 Mn in Seed funding. The round was led by Zeropearl VC and Eleven, with strategic participation from healthcare veteran Sunil Sachdeva, co-founder of Medanta.
- Slayd (Ecommerce / Ecommerce Enablers – B2C): Early-stage enabler Slayd raised $156K in an unlisted round backed entirely by active micro-VC AJVC.
Thursday, September 17, 2026
- DheyaTech (Advanced Hardware & Tech / Aerial Vehicles – B2B): Aerial vehicle and drone technology startup DheyaTech secured $5.1 Mn in fresh capital. The round was led by Avaana Capital, with co-investment from Unimech Aerospace and Manufacturing, pointing to expanding synergies between aerospace manufacturing and autonomous aerial tech.
- Enlight Metals (Enterprise Services / Manufacturing Solutions – B2B): Industrial and manufacturing solutions provider Enlight Metals picked up $1.5 Mn from Exar North Group.
- Kiddo (Consumer Services / Quick Commerce – B2C): Targeting hyper-fast delivery ecosystems, Kiddo bagged $1.3 Mn in a Pre-Seed round entirely funded by Campus Fund, which targets student and young-entrepreneur-led enterprises.
- Factrika (Enterprise Services / Manufacturing Solutions – B2B): Digital manufacturing infrastructure platform Factrika secured $928K in a Seed round led by Info Edge Ventures, reinforcing Info Edge’s long-standing thesis on B2B marketplaces and industrial tech.
- Ecosys (Consumer Services / Hyperlocal Services – B2C): Hyperlocal services provider Ecosys raised $521K in a Pre-Series A round. The round was led by the GVFL Prarambh Fund and Proteus Partners, alongside angel investments from Puru Gupta and Sreejith Moolayil.
Friday, September 18, 2026
- MoroMaa (Ecommerce / D2C – B2C): Direct-to-consumer brand MoroMaa secured $156K from active early-stage backer AJVC.
- Beijan (Advanced Hardware & Tech / Defence Tech – B2B/B2G): Bolstering India’s indigenous defense capabilities, Beijan raised $156K from AJVC.
- Zinara (Ecommerce / D2C – B2C): D2C brand Zinara secured an undisclosed amount of capital in a strategic round backed by actor and entrepreneur Nikita Dutta.
Supporting Data & Market Dynamics
To fully grasp the mechanics behind this week’s 82% funding drawdown, analysts point to several cyclical and structural factors governing the venture capital pipeline:
- The Late-Stage Drought: The primary driver of week-on-week volatility in Indian startup funding is the presence—or absence—of mega-rounds ($50 Mn+). While the previous week benefited from multiple large-ticket growth and late-stage checks, this week’s capital allocation was dominated by early-stage seed and pre-seed rounds (accounting for the vast majority of the 12 transactions). Flam’s $40 Mn Series B was the sole outlier holding up the aggregate total.
- Sectoral Realignment: Enterprise SaaS, deeptech (semiconductors, drones, defense), and B2B manufacturing solutions captured disproportionate investor mindshare. Conversely, consumer internet and quick commerce faced tighter scrutiny as unit-economics and path-to-profitability metrics continue to be heavily audited by risk-averse institutional funds.
- Micro-VC Resilience: Micro-funds like AJVC, Campus Fund, and early-stage syndicates demonstrated that deal-making at the grassroots level remains active. These funds are increasingly insulating themselves from macroeconomic shocks by writing smaller, lower-risk initial checks.
Fund Ecosystem & Strategic Developments
Beyond direct equity checks into operating startups, the broader venture capital and private equity infrastructure witnessed notable fund-raising activities and institutional partnerships this week:
- AJVC Expands LP Base: Prolific early-stage investor AJVC announced that prominent private equity firm Novastar Partners has come on board as a limited partner (LP) for its fund. This institutional validation provides AJVC with enhanced dry powder to scale its early-stage thesis across emerging D2C and deeptech segments.
- Finvolve and Activate Secure Fresh Capital: Both Finvolve and Activate successfully closed fresh capital infusions for their respective vehicles, signaling continued domestic and regional LP appetite for alternative asset classes.
- Deeptech Mega-Fund Launch: In one of the most significant structural announcements of the week, Asiana Fund and JC Capital announced a strategic partnership to launch a dedicated ₹1,000 Cr deeptech-focused fund. This mega-vehicle aims to bridge the perennial capital deficit plaguing Indian hardware, semiconductor, space-tech, and advanced engineering startups, providing them with the long-term risk capital necessary to commercialize deep science research.
Regulatory Backdrop: The MDR on UPI Debate
While founders and investors navigated financing rounds, the macro-discourse across corporate India was dominated by intense debates regarding the potential introduction of Merchant Discount Rates (MDR) on UPI transactions.
For years, zero-MDR on UPI has been heralded as the foundational catalyst driving India’s digital payments revolution, pushing transaction volumes into the tens of billions monthly. However, payment gateway operators, fintech startups, and banking partners have increasingly voiced sustainability concerns regarding the zero-fee model, citing mounting infrastructure and cybersecurity maintenance costs.
The ongoing policy discussions—though not directly resulting in immediate legislative changes this week—have cast a shadow of caution over fintech and consumer-facing technology investments. Institutional investors are closely monitoring how regulatory compromises might alter the revenue models of payment aggregators and neo-banks, temporarily pausing large-scale deployments in the broader fintech sector until regulatory clarity emerges.
Implications for Founders and Investors
The steep decline in weekly funding should not be misconstrued as a permanent structural retreat, but rather as a reflection of normalization and strategic caution.
For Founders:
- Focus on Fundamentals: With late-stage capital becoming erratic, startups cannot rely on easy bridge rounds. Founders must prioritize sustainable unit economics, low burn rates, and clear paths to operational break-even.
- Pivot Toward Deeptech and B2B: As demonstrated by the launch of the ₹1,000 Cr Asiana-JC Capital fund and strong backing for VerifAIX and DheyaTech, government-backed pushes toward domestic manufacturing, defense self-reliance, and deeptech innovation offer fertile ground for non-consumer startups seeking capital.
For Investors:
- Hedging via Micro-VCs: Institutional investors are increasingly leveraging micro-VC partnerships (such as Novastar’s backing of AJVC) to de-risk early-stage exposure while maintaining skin in the game across emergent consumer and enterprise trends.
- Regulatory Vigilance: Investors in fintech and consumer internet must factor in impending regulatory shifts, particularly concerning payment monetization and data privacy compliance, before committing heavy capital to transaction-heavy ecosystems.
As the third quarter of 2026 draws to a close, the Indian startup ecosystem remains resilient, albeit navigating a more disciplined, valuation-conscious, and policy-sensitive market environment.