Dalal Street’s Golden Era: Inside India’s Startup IPO Wave
Main Facts: A Record-Breaking Surge on the Bourses
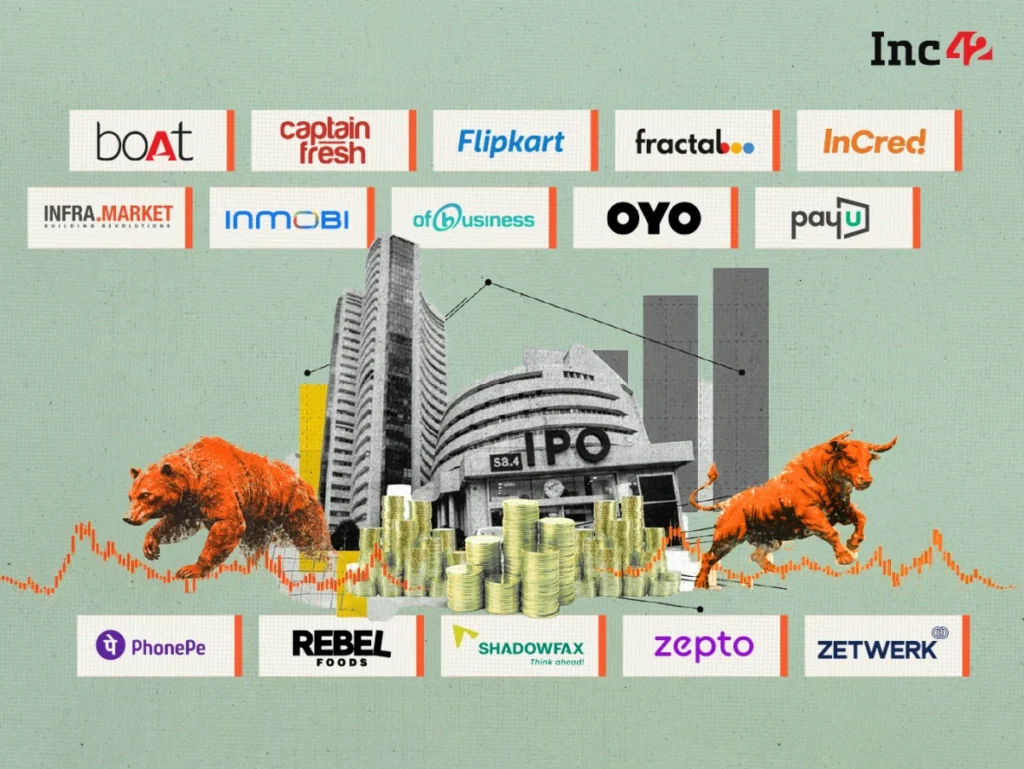
India’s financial capital cemented its status as a founder’s paradise in 2025, establishing an unprecedented benchmark for the country’s new-age tech ecosystem. Across the year, 18 Indian startups successfully crossed the threshold of public listings, collectively mobilizing a staggering INR 41,248 Cr from the public markets.
This historic capitalization surge was underpinned by a confluence of macroeconomic tailwinds and progressive regulatory evolution. Robust national gross domestic product (GDP) growth projections provided a steady tailwind, significantly buoying institutional and retail investor appetite. Simultaneously, proactive regulatory reforms spearheaded by the Securities and Exchange Board of India (SEBI) eliminated critical bottlenecks. Streamlined Draft Red Herring Prospectus (DRHP) filings substantially reduced bureaucratic friction, while flexible Employee Stock Ownership Plan (ESOP) guidelines empowered founders to preserve meaningful equity ownership as their enterprises matured.
The retail participation component proved equally transformative. The total volume of demat accounts eclipsed the 20-crore milestone, injecting unprecedented liquidity into the domestic capital pools. Offer for Sale (OFS) mechanisms dominated public issues throughout the period, providing a reliable liquidity exit for early-stage venture capital backers and angel investors who had supported these digital-native enterprises through their infancy.
Market sentiment transitioned away from unbridled growth-at-all-costs metrics. Instead, public market investors enforced strict discipline, rewarding enterprises that prioritized unit economics, sustainable operational growth, and robust corporate governance over pure top-line expansion.
Chronology of Public Market Transitions (2025–2026)
The momentum generated in 2025 served as a springboard for subsequent market activity. By mid-2026, thirteen additional new-age technology companies had completed their Dalal Street debuts.
- Early 2025: Regulatory frameworks modernized, paving the way for confidential pre-filings and simplified compliance. High-profile enterprises like OYO (rebranded as PRISM) and Zepto began laying the groundwork for public floats.
- Mid to Late 2025: Startups such as Amagi, Fractal, and Shadowfax filed their draft papers, clearing regulatory hurdles by the fourth quarter.
- Early 2026: ESDS Software Solution, Klassroom, RentoMojo, SEDEMAC, Kissht, LEAP India, and Shiprocket recorded high-profile market debuts. Notable highlights included ESDS listing at a stellar 76% premium on the NSE, alongside strategic market entries from deeptech and logistics players.
- Mid-to-Late 2026: The pipeline expanded aggressively. Over twenty-four startups formally filed their DRHPs with SEBI, while more than twenty-five others finalized structural preparations for upcoming floats. Heavyweights including OYO, Razorpay, and Zetwerk targeted capital raises exceeding INR 34,000 Cr, positioning 2026 as one of the most prolific years in Indian corporate history for startup initial public offerings.
Supporting Data: The 2026 IPO Ecosystem Matrix
The following comprehensive compilation outlines key financial and operational metrics for prominent Indian technology enterprises navigating the public markets, derived from regulatory filings and market reports:
| Name | Founded | Sector | Total Funding | Key Investors | Revenue (FY25/Latest) | DRHP Status | IPO Size (INR Cr) | Valuation (INR Cr) |
|---|---|---|---|---|---|---|---|---|
| AceVector | 2010 | Ecommerce | – | SoftBank, eBay, Nexus | INR 395 Cr | Filed | INR 300 Cr + OFS | Undecided |
| Acko | 2016 | Insurtech | $458 Mn | General Atlantic, Amazon | INR 2,836.8 Cr | Yet To File | $300–$400 Mn | Undecided |
| Amagi | 2008 | SaaS | $320 Mn | General Atlantic, Accel | INR 1,162.6 Cr | Listed | INR 1,788.6 Cr | INR 7,966 Cr |
| Aye Finance | 2014 | Fintech | $485 Mn | Google, ABC Impact | INR 1,459.7 Cr | Listed | INR 1,010 Cr | INR 3,183 Cr |
| boAt | 2016 | D2C | $177 Mn | Warburg Pincus, Qualcomm | INR 3,073.3 Cr | Filed | INR 1,500 Cr | Undecided |
| C5i | 2000 | Enterprise AI | $55 Mn | Nuvama, 360 ONE | INR 545.3 Cr | Filed | INR 1,000–1,200 Cr | Undecided |
| CarDekho | 2008 | Auto Tech | $750 Mn | Peak XV, Google, Hillhouse | INR 2,795 Cr | Yet To File | INR 3,500 Cr | INR 13,000–15,000 Cr |
| Cult.fit | 2016 | Ecommerce | $650 Mn | Zomato, Accel, Temasek | INR 1,215 Cr | Yet To File | INR 2,500 Cr | INR 17,200 Cr |
| ESDS Software | 2005 | Cloud/Data | $47.3 Mn | Ashish Kacholia | INR 472.2 Cr | Listed | INR 720 Cr (Fresh) | Undecided |
| Fibe | 2015 | Fintech | $266 Mn | TPG, Norwest, Eight Roads | INR 1,584.6 Cr | Filed | INR 750 Cr + OFS | Undecided |
| Flipkart | 2007 | Ecommerce | NA | Walmart, Google | INR 20,493 Cr | Yet To File | Undecided | Undecided |
| Fractal | 2000 | SaaS | $685 Mn | TPG, Apax Partners | INR 3,299.7 Cr | Listed | INR 2,833.9 Cr | INR 15,480 Cr |
| InCred | 2016 | Fintech | $318 Mn | FMO, KKR, Paragon | INR 1,873.6 Cr | Filed | INR 1,250 Cr + OFS | INR 15,000–22,500 Cr |
| Infra.Market | 2016 | Ecommerce | $415 Mn | Tiger Global, Accel | INR 18,472 Cr | Filed | INR 5,000 Cr | Undecided |
| Kissht | 2015 | Fintech | $140 Mn | Vertex, Zodius | INR 2,179.3 Cr | Listed | INR 925.9 Cr | INR 3,511.2 Cr |
| Klassroom | 2016 | Edtech | $2 Mn | ah! Ventures, LetsVenture | INR 23 Cr | Listed | INR 39 Cr | INR 155.4 Cr |
| LEAP India | 2013 | Logistics | $184 Mn | KKR, Sixth Sense | INR 729.5 Cr | Listed | INR 2,480 Cr | INR 7,004 Cr |
| Moneyview | 2016 | Fintech | $190 Mn | Accel, Nexus Ventures | INR 2,339.1 Cr | Filed | INR 750 Cr + OFS | Undecided |
| OYO (PRISM) | 2013 | Travel Tech | $3.47 Bn | Microsoft, Red Lions | INR 6,252.8 Cr | Filed | INR 6,650 Cr | INR 62,500–71,000 Cr |
| PhonePe | 2015 | Fintech | $2.29 Bn | Walmart, General Atlantic | INR 7,115 Cr | Filed | INR 10,700–13,400 Cr | INR 1.07 Lakh–1.3 Lakh Cr |
| Razorpay | 2014 | Fintech | $816 Mn | Peak XV, Lone Pine | INR 3,783 Cr | Filed | INR 4,760–6,664 Cr | INR 47,600–66,640 Cr |
| RentoMojo | 2014 | Ecommerce | $45 Mn | Accel, Chiratae, Bain | INR 387 Cr | Listed | INR 150 Cr + OFS | INR 5,206 Cr |
| SEDEMAC | 2007 | Deeptech | $107 Mn | A91, Xponentia | INR 1,058.4 Cr | Listed | INR 1,087 Cr | INR 5,970 Cr |
| Shiprocket | 2017 | Logistics | $323 Mn | Temasek, Bertelsmann | INR 2,024 Cr | Listed | INR 1,617 Cr | INR 9,531 Cr |
| Zepto | 2021 | Quick Commerce | $1.60 Bn | Y Combinator, General Catalyst | INR 22,625 Cr | Filed | INR 8,010 Cr + OFS | Undecided |
| Zetwerk | 2018 | Ecommerce | $793 Mn | Greenoaks, Lightspeed | INR 12,798 Cr | Filed | INR 4,284 Cr | INR 38,000 Cr |
Official Responses and Industry Perspectives
Market leaders and venture capitalists emphasize that the structural maturity of India’s startup sector has redefined investor expectations.
"Besides the readiness that startups showed in their unit economics, there is also an increase in the founders committing to their businesses for the next couple of decades and growing their businesses by adding adjacent profit pools—something that the public markets reward handsomely," observed Ashish Kumar, co-founder and general partner at Fundamentum Partnership.
This sentiment is echoed across institutional leadership circles, where an operational transition toward disciplined capital management has taken precedence.
"IPO-bound startups in 2026 will be increasingly defined by their ability to demonstrate predictable cash flows, sustainable unit economics, and operational discipline rather than headline growth alone. Public market investors will place greater emphasis on governance, capital efficiency, and long-term value creation," stated Rehan Yar Khan, managing partner at Orios Venture Partners.
Macroeconomic Implications and Emerging Headwinds
While the domestic capital environment remains fundamentally robust, the transition into 2026 has introduced notable complexities.
- Moderating Retail and Foreign Institutional Flows: Average retail subscription levels have begun to stabilize, while Foreign Institutional Investors (FIIs) have adopted a more defensive posture. This caution stems from persistent geopolitical friction, notably ongoing conflicts in West Asia, alongside muted secondary market performance in select sectors.
- Valuation Recalibration: Public market investors are applying stringent filters to prospective listings. Unprofitable cash-burning enterprises face increased scrutiny, forcing several late-stage decacorns—such as Curefoods, Zepto, and PhonePe—to strategically pace or temporarily defer their listing timelines to prioritize fundamental cash-flow positivity.
- Deepening Domestic Liquidity: Despite foreign capital pullbacks, domestic institutional investors (DIIs) and retail mutual fund inflows have cushioned the Indian public markets, ensuring that well-managed, cash-generative technology startups continue to find deep liquidity at home.
As regulatory transparency deepens and business models mature, India continues to solidify its competitive standing as the primary nexus for startup initial public offerings across emerging global markets.