Market Analysis: Gold Prices Face Headwinds Amid Strong Dollar and Persistent High Interest Rates
By Sandal Khan
Business Desk, Zee Media
Updated: October 04, 2026, 10:31 AM IST
Introduction: The State of the Precious Metal Market
As of October 4, 2026, the global precious metals market remains caught in a tight vice. Gold, traditionally viewed as a "safe-haven" asset, is currently struggling to maintain its momentum as it grapples with a formidable combination of macroeconomic pressures. The primary culprits behind this stagnation are the continued strength of the U.S. dollar and the persistent high-interest rate environment fostered by central bank policies globally.
Investors are currently recalibrating their portfolios as the opportunity cost of holding non-yielding assets like gold becomes increasingly difficult to justify. While geopolitical tensions and lingering inflationary concerns provide some underlying support, the dominant market narrative remains defined by the strength of the greenback and the yield attractiveness of fixed-income securities.
Main Facts: Why Gold is Under Pressure
The current stagnation in gold prices is not an isolated event but rather a byproduct of global monetary tightening. To understand the current climate, one must look at three specific pillars affecting the market today:
- The U.S. Dollar Dominance: Gold is denominated in U.S. dollars. When the dollar gains strength against a basket of other major currencies, gold becomes more expensive for international buyers. This leads to a decline in demand, which subsequently suppresses price growth.
- High-Interest Rate Environment: Unlike stocks, which may offer dividends, or bonds, which pay regular interest, gold does not produce a cash flow. When central banks maintain high interest rates to combat inflation, investors flock toward bonds and savings accounts that offer guaranteed returns. This increases the "opportunity cost" of holding gold, leading to liquidation of bullion holdings in favor of yield-generating assets.
- The Inverse Relationship: Historically, there has been a strong inverse correlation between real interest rates and gold. As real rates—nominal rates minus inflation—remain elevated, the incentive to hold bullion diminishes significantly, keeping a ceiling on the metal’s price.
Chronology: A Trajectory of Market Sentiment
The journey to this current state has been marked by several key developments throughout 2026:
- Q1 2026 (The Policy Pivot): Early in the year, markets were optimistic that central banks would pivot toward aggressive rate cuts. Gold prices saw a brief rally as investors anticipated a loosening of monetary policy.
- Q2 2026 (Inflation Persistence): By the second quarter, it became clear that inflation was proving "stickier" than anticipated. Data releases indicated that consumer prices remained above target, forcing central banks to signal that "higher for longer" was the new baseline for interest rates.
- Q3 2026 (Dollar Surge): Mid-year, the U.S. economy displayed unexpected resilience in labor market reports and consumer spending, fueling a rally in the U.S. Dollar Index (DXY). This surge directly pressured commodities, with gold retreating from its previous highs.
- October 2026 (The Current Standstill): As of today, the market has reached a state of equilibrium, where the downside is limited by geopolitical concerns, but the upside is blocked by the strength of the U.S. monetary regime.
Supporting Data: Market Metrics
Market analysts suggest that the current price stability is a reflection of a "wait-and-see" approach adopted by institutional investors.
- ETF Outflows: Data from major gold-backed Exchange Traded Funds (ETFs) shows a consistent trend of outflows over the last four weeks. Investors are moving capital away from bullion funds and into money market funds, which currently offer attractive yields.
- Real Yields: The 10-year Treasury Inflation-Protected Security (TIPS) yield, a critical benchmark for gold investors, has remained in positive territory, consistently hovering above the 2% threshold. This high real yield environment is a classic headwind for gold.
- Central Bank Buying: While private investors are selling, central banks in emerging markets continue to diversify their reserves by purchasing gold. This institutional buying is acting as a "floor," preventing a more significant price collapse.
Official Responses and Expert Outlook
Economists and financial analysts are divided on the short-term outlook but largely agree on the medium-term risks.
The Hawkish Perspective:
"The current economic data does not support a bull run for gold," says a lead strategist at a top-tier investment bank. "As long as the labor market remains tight and the Federal Reserve maintains a hawkish bias, the dollar will continue to drain the momentum from precious metals. We expect gold to remain range-bound until there is a clear signal that the cycle of tightening has ended."
The Geopolitical Buffer:
Other analysts point to the "fear premium." Despite the economic headwinds, gold is holding up better than it would have in previous decades under similar interest rate conditions. Experts attribute this to ongoing conflicts and the fragmentation of global trade, which keeps gold in demand as a hedge against systemic instability.
Implications: What This Means for Investors
For the average investor or consumer, the current market situation carries several implications:
1. Jewelry and Consumer Demand
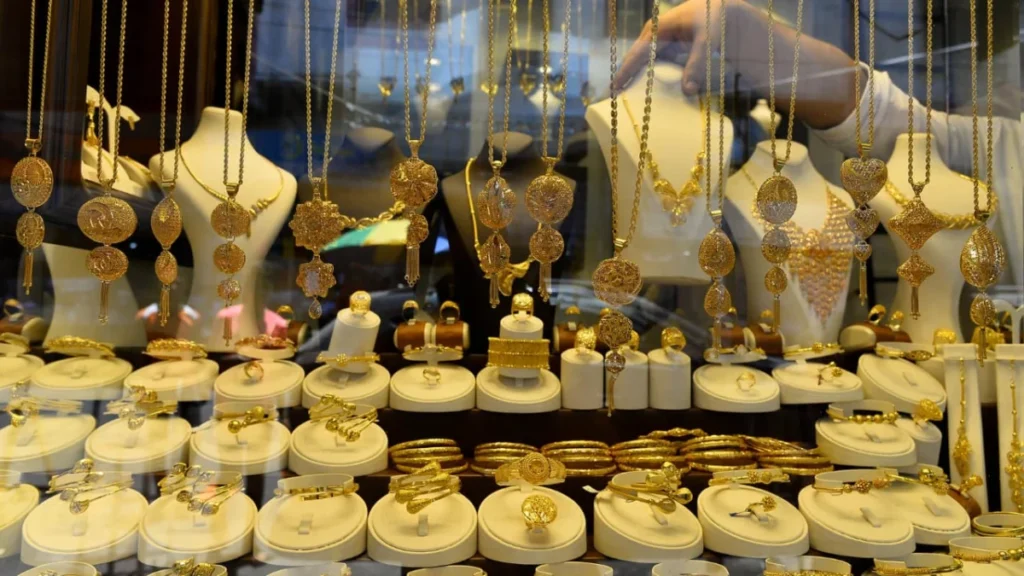
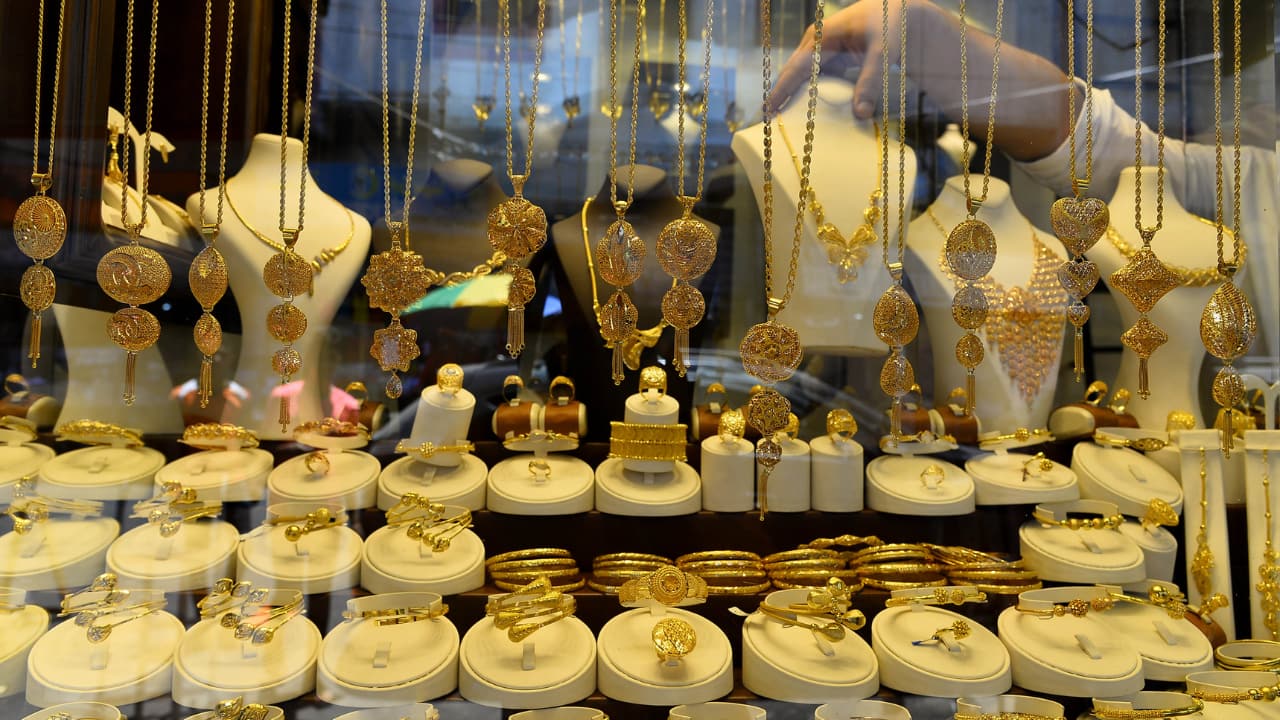
In countries like India, where gold is a cultural staple, the price stability is a double-edged sword. While the lack of volatility makes budgeting for weddings and festivals easier, the high price levels relative to the start of the decade continue to dampen discretionary consumer demand. Retailers are reporting lower volume, even if the value of sales remains high.
2. Portfolio Diversification
Financial advisors suggest that the current environment is a test of portfolio discipline. For long-term investors, gold serves as a vital component of a diversified portfolio—not necessarily for its short-term gains, but for its role as a hedge against currency devaluation. Investors are advised to look at gold through a long-term lens rather than reacting to the daily fluctuations driven by interest rate news.
3. The Future of Non-Yielding Assets
If the "higher for longer" narrative persists into 2027, we may see a fundamental shift in how precious metals are valued. Investors might demand higher "utility" from gold-related investments, leading to an increase in gold-mining stocks or derivatives that offer a form of yield or dividend, rather than holding physical bullion which carries storage and insurance costs without any yield.
Geopolitical Fragility and the Gold Hedge
One cannot discuss the price of gold without addressing the shadow of global instability. In 2026, the world remains characterized by localized conflicts and trade protectionism. In such an environment, gold serves as a "neutral" asset. Unlike the U.S. dollar, which is subject to the monetary policy of a single nation, gold remains a global currency that no government can print.
While interest rates are currently the dominant force, a sudden geopolitical shock could quickly reverse the trend. If investors lose confidence in the stability of fiat currencies or the international banking system, gold could detach from its current correlation with the dollar and see a surge in demand, regardless of the interest rate environment. This "tail risk" is exactly why central banks and prudent investors continue to hold the metal.
Conclusion: Navigating the Stagnation
The precious metal market is currently in a state of suspended animation. The conflict between the economic reality of high interest rates and the psychological necessity of a safe-haven asset creates a complex landscape.
For the short term, investors should anticipate continued volatility tied to every piece of economic data released by the Federal Reserve and other major central banks. The stronger the dollar, the more likely gold is to remain under pressure. However, the structural support provided by central bank reserve diversification and the lingering global geopolitical uncertainty ensures that gold remains a critical, albeit currently dormant, powerhouse in the financial world.
As we move toward the end of 2026, the market will continue to watch for any shifts in monetary policy. Until that pivot occurs, the precious metal will likely remain a "wait-and-see" asset, rewarding those with patience while punishing those who expect immediate, high-growth returns in an environment designed for consolidation.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Investors should consult with a qualified financial advisor before making any investment decisions.